All articles
M&G/BauMont €70m Munich deal (Oct 2026): what fresh institutional demand means for yields
M&G’s BauMont bought a Munich residential ensemble for more than €70m (announcement 30 Sep 2026). This article explains what the purchase — and the €200m German platform with Reneo — implies for yield pressure in Munich submarkets, using Feldmoching as a Munich case study and correcting a geography error about Altglienicke.
What happened — the facts
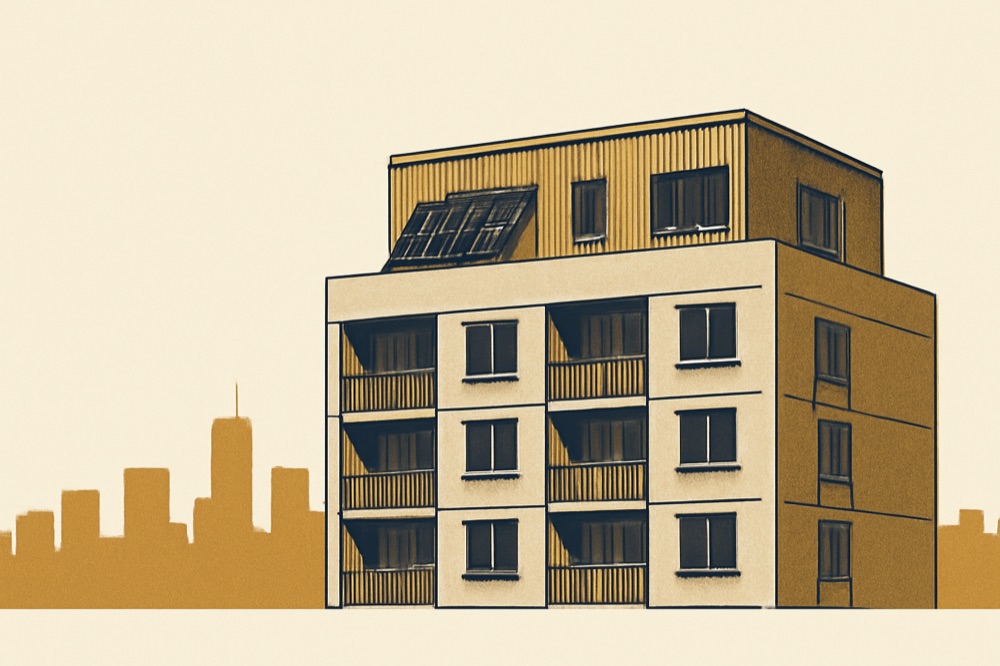
M&G Real Estate’s value‑add manager BauMont announced entry to Germany with a strategic partnership with operator Reneo and an initial Munich acquisition announced on 30 September 2026. The launch deal is described in the press coverage as a brown‑to‑green residential investment in Munich with a purchase and transformation budget of more than €70 million; the platform target is more than €200 million of investment over the next 12 months. The property is reported to be in Obersendling and the plan includes an energy upgrade (reported from energy class H to class A / KfW‑55 standard), rooftop and structural extensions adding roughly 1,700 m² and more than 30 new flats to lift the scheme to above 250 units. (Sources: M&G/Reneo press coverage dated 30 Sep–2 Oct 2026.)
Why institutions buying value‑add homes matters for Munich yields
Large, well‑funded investors like M&G buy at scale and with hold‑periods and financing structures that differ from private buyers and small funds. When they target brown‑to‑green upgrades and density gains (roof extensions, infill, refurbishments) they can pay a premium over a purely 'as‑is' yield because they expect to improve net operating income and to reduce regulatory and obsolescence risk through energy upgrades. A focused pipeline — here, a stated platform >€200m — concentrates buying power into the submarkets where feasibility of densification and retrofit is highest. The immediate impact is selective yield compression: prices rise (and running yields fall) in parts of the city where these value‑add interventions are executable, while more constrained or peripheral micro‑markets see little direct bidding pressure.
Case study: Feldmoching (Munich)
Feldmoching‑Hasenbergl is a northern Munich district with a mix of post‑war blocks, single‑family pockets and good S‑bahn connections to the centre. Its characteristics are typical of 'outer' Munich: lower headline rents than inner districts, larger parcel sizes and a higher share of properties where rooftop and infill add‑ons are technically possible. That combination makes Feldmoching a plausible target for value‑add players seeking to create additional units and capture rent uplift after refurbishment. If institutional platforms prioritise exactly these engineering‑friendly submarkets, expect capital to narrow the pricing gap between Feldmoching and better‑located suburbs where retrofit with density is harder to execute. This is a directional effect — feasibility and local planning rules remain decisive, and outcomes will vary block‑by‑block.
On Altglienicke — a geography check and what it shows
Important correction: Altglienicke is a locality in Berlin (Treptow‑Köpenick), not in Munich. I mention it because the name appears in some investor commentary as an example of a peripheral, engineering‑friendly location where density and retrofit programmes attract institutional buyers. The comparison is useful conceptually: when institutions target peripheral suburbs with build‑up potential — whether in Munich, Berlin or other cities — the market mechanism is the same: concentrated capital chases a narrow set of technical opportunities, compressing yields there while leaving other pockets unchanged. For readers comparing cities, check municipal building codes and local 'milieuschutz' or preservation zones before assuming rooftop work or extensions are feasible.
What foreign buyers should watch
1) Planning risk: institutional appetite only matters where extensions or energy upgrades are deliverable within local rules. 2) Competition: expect targeted submarkets to see faster price discovery and occasional auction‑style competitive bidding among funds. 3) Exit timing and liquidity: value‑add plays rely on execution; long hold periods reduce short‑term yield volatility but increase exposure to regulatory change. 4) Local operating partner: M&G uses Reneo as operator; for non‑German investors a local technical partner and experienced legal counsel are essential. This article does not provide personalised investment or tax advice; consult a German notary, local planning lawyer and tax adviser for transaction‑specific counsel.
Nothing on this page is investment, tax or legal advice. Price bands are indicative asking prices and disagree between sources by design. Verify every figure with a qualified German notary, tax adviser (Steuerberater) or lawyer before committing capital.